Most homeowners deal with a roof claim once or twice. The adjuster deals with them every day. This guide closes some of that gap: how a Texas claim moves, what your policy terms mean in plain numbers, and where a roofer fits in and where one does not.
General education, not legal or insurance advice. Your policy and your insurer decide coverage.
Does homeowners insurance cover roof damage?
Usually, when the damage is sudden and comes from a covered event such as hail, wind or a falling tree, subject to your deductible and policy terms. It does not pay for a roof that is simply old or worn out. The Texas Department of Insurance says this directly in its roof guide.
The details that change the answer for a specific house are in the policy: a separate wind and hail deductible, a roof paid at actual cash value, or a cosmetic damage exclusion. Our page on what homeowners insurance covers on a roof goes through them one by one.
Call a roofer or your insurer first?
Have a reputable local roofer inspect first so you know whether there is real damage before you open a claim. If there is, report it to your insurer promptly. Photograph what you can see, make temporary repairs to stop leaks, and keep the receipts. Policies set deadlines for reporting, so do not wait.
A typical Texas roof claim runs like this:
- Inspection and dated photos.
- You report the claim and get a claim number.
- The adjuster inspects.
- The insurer sends its estimate and a first payment.
- The roof is repaired or replaced.
- The final invoice goes in and any recoverable depreciation is released.
Texas law also puts deadlines on your insurer, including written acceptance or rejection within 15 business days of receiving everything it asked for, under Insurance Code Chapter 542. The full walk-through, with every deadline, is on our claim process page.
How wind and hail deductibles work
Many Texas policies carry a separate wind and hail deductible set as a percentage of your dwelling coverage, not of the claim. On a home insured for 300,000, a 2% deductible is 6,000. You pay that amount toward the work, and the insurer subtracts it from what it pays. No contractor can legally cover it for you.
Texas Insurance Code Chapter 707 requires the policyholder to pay the deductible, and Business and Commerce Code §27.02 makes waiving, absorbing or rebating it a Class B misdemeanor for the contractor (HB 2102, 2019). We never do it. Worked examples at different coverage amounts are on our deductibles page.
Actual cash value vs. replacement cost
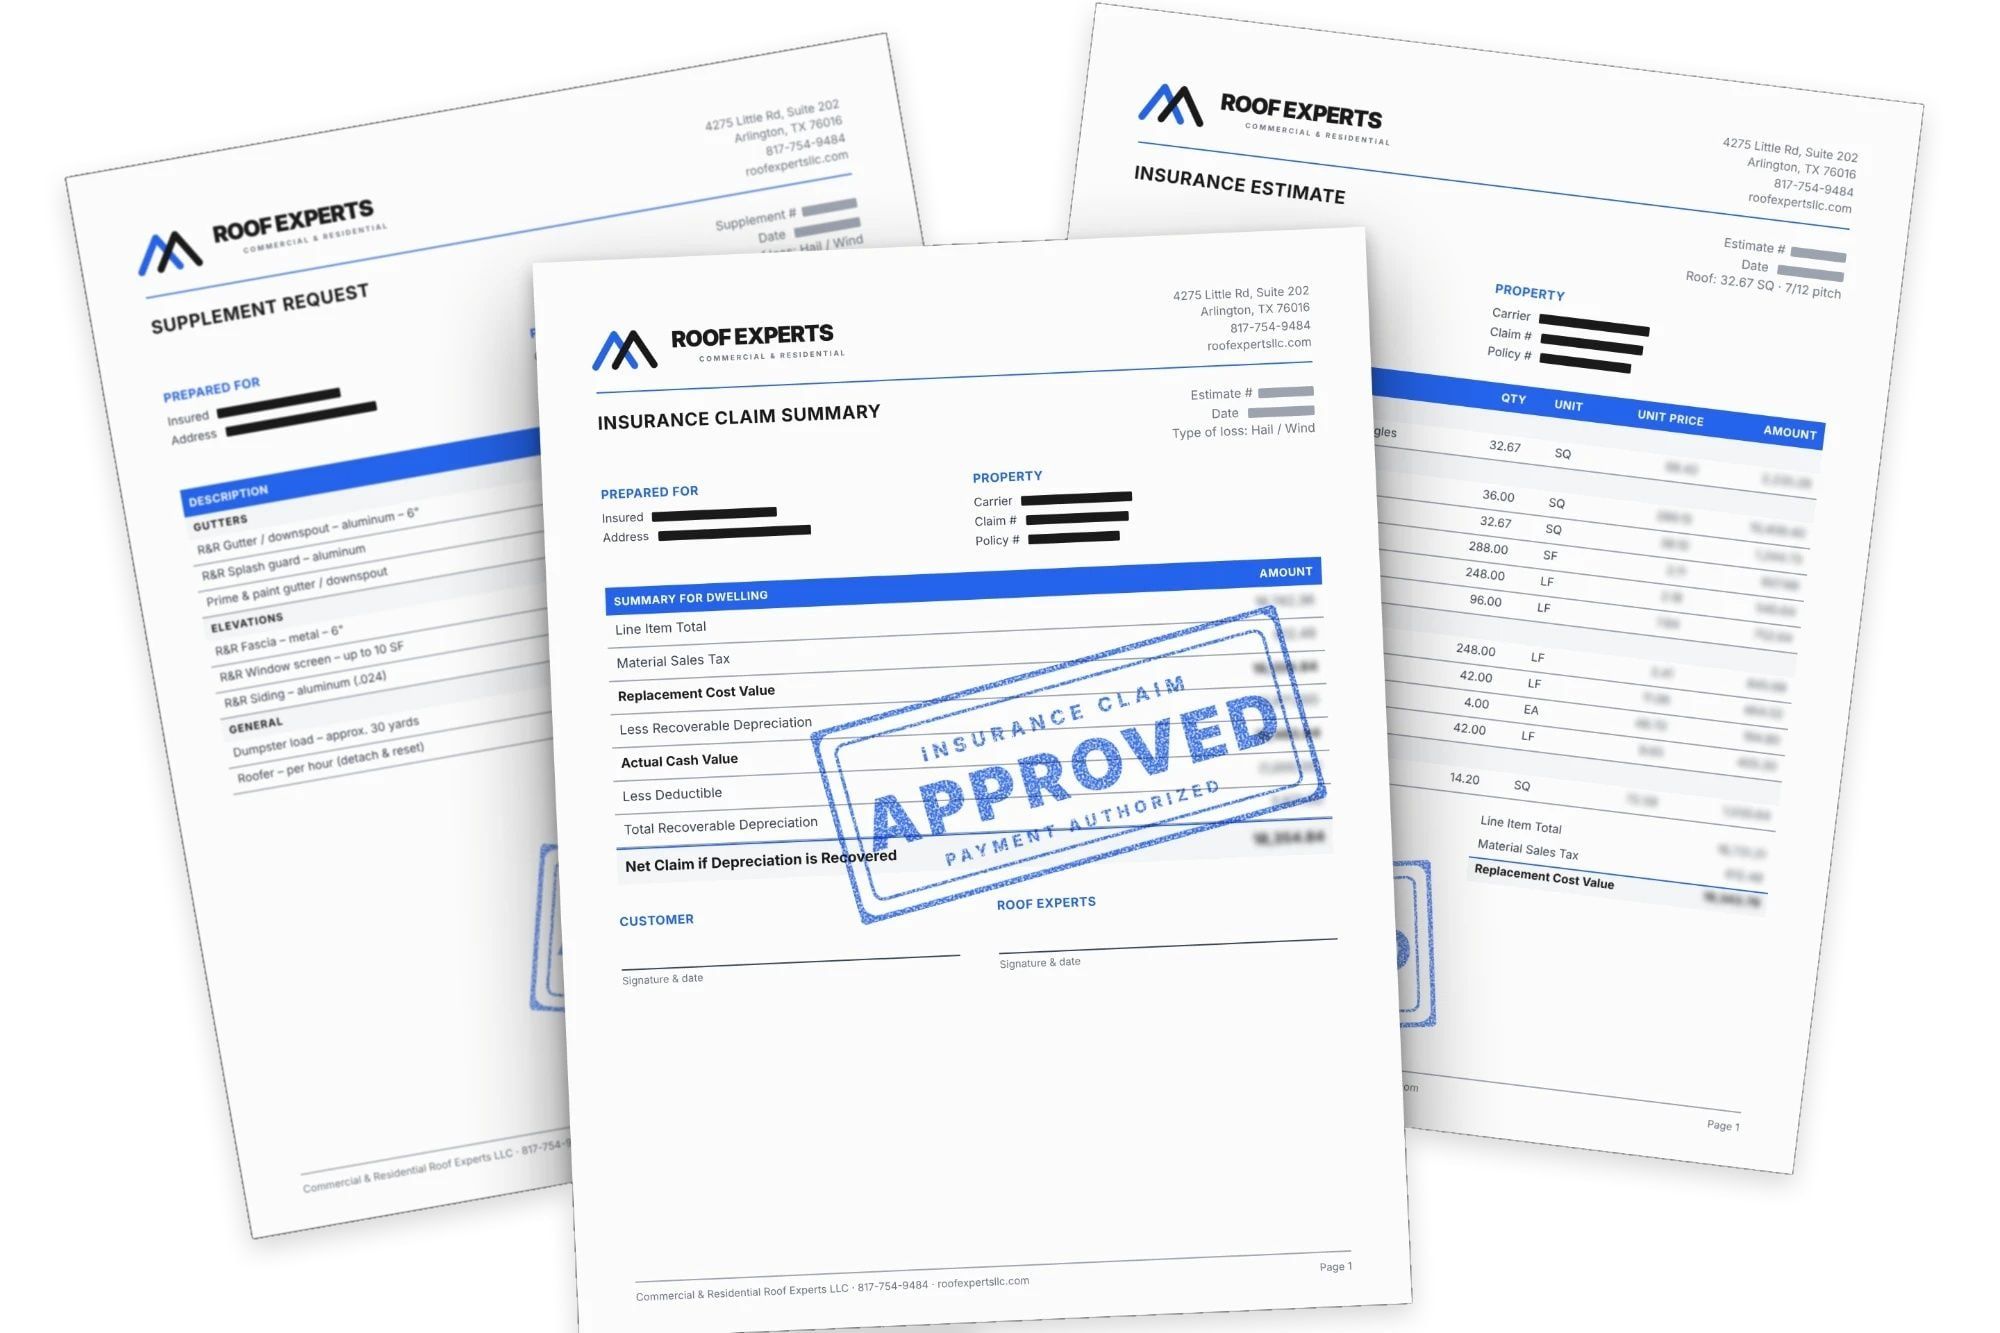
A replacement cost policy pays what it costs to replace the roof at today’s prices, minus your deductible, usually in two checks. The second check releases the recoverable depreciation after the work is done. An actual cash value policy subtracts depreciation for age and wear, so an older roof pays less and there is no second check.
Your declarations page says which one applies to your roof, and the Texas Department of Insurance notes that some companies move older roofs to actual cash value at renewal. If you have a mortgage, expect the lender’s name on the check. Our ACV vs. replacement cost page explains both checks with a worked example.
What happens at the adjuster meeting
The adjuster inspects the roof, gutters, vents and other soft metals, photographs and measures, and writes the insurer’s estimate. You should be there, and it helps to have your roofer there too, so the damage already documented gets seen and recorded. We attend these inspections. We do not negotiate your claim.
That line comes from Texas Insurance Code §4102.163: a contractor may not act as a public adjuster or advertise to adjust claims on a property it is working on, or may work on. What to have ready, and what to ask before the adjuster leaves, is on our adjuster meeting page.
If your roof claim is denied or underpaid
Ask for the decision in writing with the policy language it relies on, then ask the insurer to review it with fresh photos or a contractor’s estimate. If the dispute is about the amount, check your policy for an appraisal clause. If you believe the claim was handled unfairly, you can file a complaint with the Texas Department of Insurance.
The Texas Department of Insurance lists these options, along with public adjusters, mediation and lawsuits, on its page for homeowners who disagree with a claim decision. Our denied roof claim page explains each one and when people usually reach for it.
What we do on a claim, and what we don’t
We handle the roofing side of the claim: the inspection, the evidence, the scope and the work. The claim itself stays yours. You file it, you talk to your insurer about coverage, and you pay your deductible. That split is what Texas law requires, and it keeps the process clean for everyone involved.
| We do | We don’t |
|---|---|
| Free storm inspection, slope by slope | Negotiate your settlement |
| Dated photos with scale, plus soft-metal damage | Act as your public adjuster |
| Roof measurements and an itemized written scope | Speak for you on coverage questions |
| Attend the adjuster’s inspection | Waive, rebate or pay any part of your deductible |
| Do the repair or replacement and send the final invoice | Promise what your insurer will pay |
We are based at 4275 Little Rd #202 in Arlington, in business since 2017, and registered with the City of Arlington. If hail or wind has hit your roof, start with a free storm inspection or call (817) 754-9484. Arlington homeowners can also read our Arlington insurance claim page.
Texas roof claim guides
- Actual Cash Value vs. Replacement Cost on a Roof Claim in Texas and DFWWhat actual cash value and replacement cost mean for a roof claim, how recoverable depreciation works, and why the check has your lender's name on it.
- Meeting the Insurance Adjuster for a Roof Claim in DFWWhat happens when the insurance adjuster inspects your roof, why your roofer should be there, and how to prepare for the visit.
- The Texas Roof Insurance Claim Process, Step by Step, for DFW HomeownersWho to call first after hail, each step of a Texas roof claim, the deadlines your insurer must meet, and the paperwork worth keeping.
- Wind and Hail Deductibles in Texas: What DFW Homeowners Actually PayPercentage wind and hail deductibles explained with worked examples, plus the Texas law that bars contractors from waiving or paying them.
- Roof Insurance Claim Denied in Texas: Next Steps for DFW HomeownersWhy Texas roof claims get denied or underpaid, and the options homeowners have: review, appraisal, a TDI complaint and professional help.
- What Homeowners Insurance Covers on a Roof in Texas and DFWWhat a Texas homeowners policy usually pays for on a roof after a storm, what it leaves out, and how to check your own policy before you need it.
Sources
- Texas Department of Insurance, Steps to getting your home or car insurance claim paid
- Texas Department of Insurance, Home insurance guide
- Texas Department of Insurance, Insurance and your roof
- Texas Department of Insurance, Roofing and insurance: Know the law
- Texas Department of Insurance, If your insurer isn't paying enough or denies your claim
- Texas Department of Insurance, Impact-resistant roofing discounts
- Texas Legislature, HB 2102 (86th Legislature), enrolled text
- Texas Insurance Code, Chapter 542 (prompt payment of claims)
- Texas Insurance Code, Chapter 4102 (public adjusters; Section 4102.163)